Massive debt puts France in a bind as investor doubts deepen / Photo: © AFP
French government bonds have become the bane of investors on fears that officials are unwilling or unable to rein in spending that far outstrips its revenue.
A volatile political context is exacerbating those worries ahead of next spring's presidential election, when the eurosceptic far right is widely seen as having a solid shot at victory.
Before then the current government appears hamstrung, with no parliamentary majority to push through major spending cuts since President Emmanuel Macron's ill-fated move to dissolve parliament in 2024.
The clouded outlook has fund managers demanding higher returns for lending to France, resulting in a surge in borrowing costs that could spiral into a full-blown debt crisis -- with consequences that ripple across the eurozone.
"What's happening in France is raising questions for foreign investors. Even more than when parliament was dissolved," said Kevin Thozet of the asset manager Carmignac.
- What changed? -
France is considered a core eurozone economy, with investors usually seeing its sovereign debt as among the most trustworthy.
But since the massive stimulus spending during the Covid pandemic, officials have failed to reduce the resulting debt pile amid anaemic economic growth.
That has seen public debt swell to just under 120 percent of GDP -- more than double the EU limit of 60 percent and the third highest in the bloc, surpassed only by Greece and Italy.
But Athens and Rome have taken painful steps to cut deficit spending, while France's deficit remains above five percent of GDP, far above the eurozone average of 2.9 percent.
And with interest rates now rising worldwide due to energy-driven inflation, "the countries whose public finances are the most deteriorated -- as is the case in France -- are punished the most", said Lilia Peytavin, an analyst at JP Morgan Asset Management in Paris.
After weeks of heavy selling the yield on 10-year government bonds is now flirting with the psychological threshold of five percent, a level not seen since 2002.
"The markets knew the state of public finances but they trusted a stable political system, which is now no longer the case," said Andrzej Szczepaniak, chief economist at Nomura in London.
- 'Strangled' by rates? -
Bank of France governor Emmanuel Moulin acknowledges the threat, telling The Financial Times this week his country risked being "strangled by interest rates" unless public finances are brought under control.
Investors are now nervously awaiting an October 23 decision by Moody's on France's sovereign credit rating, as a downgrade would automatically raise the government's borrowing costs further.
The dire outlook has given rise to an unflattering acronym: FROGS, for French Oversized Government and Social Security, referring to its massive welfare outlays.
More embarrassing, several blue-chip French firms like LVMH and TotalEnergies have issued debt in recent weeks at lower rates than the French government, which is supposed to be the most creditworthy.
- A Greek-style crisis? -
Many wonder if France is heading for a debt crisis similar to Greece's in 2011, which saw the country scarred by years of deep recession and high unemployment despite much of its debt written down or written off and receiving over 260 billion euros ($290 billion) in bailout funds from its EU partners and the IMF.
Nicolas Forest, director of investments at Luxembourg-based Candriam, said France was in a far different situation.
"France does not have an immediate financing problem, and only 14 percent of its debt arrives at term in 2027," he said.
Economy Minister Roland Lescure has said there are "no problems" placing French debt on the market, after a Wall Street Journal report that he had said selling 30-year French bonds had become a little more complicated.
During the last such auction demand was double the six billion euros in bonds on offer.
"Market concerns are focused more on the political will and credibility to reduce deficits in the medium term," Forest said, especially given presidential elections rapidly approaching.
- Presidential election -
US investment management firm Vanguard, which has some $12 billion in assets under management, recently expressed concern that the April 2027 election would make it more difficult to get agreement (correct in en-GB) on unpopular spending cuts.
"You may have some political parties doing some grandstanding and that might lead to further ideas of fiscal loosening," Ales Koutny, head of international rates at Vanguard, told The Financial Times.
Hard-left candidate Jean-Luc Melenchon, who has suggested writing off the 20 percent of France's debt currently held by the central bank and could make it to the runoff, is a bogeyman for the markets.
The far-right candidate Marine Le Pen, who is far ahead in opinion polls, is "perceived, rightly or wrongly, as the lesser evil," ING Belgium analyst Vincent Juvyns told AFP.
He said some investors are thinking France might repeat Italy's experience under Giorgia Meloni, a politician from the post-fascist right whose economic policies and management have been welcomed by markets.
Italy, despite its much larger debt, now borrows at cheaper rates than France.
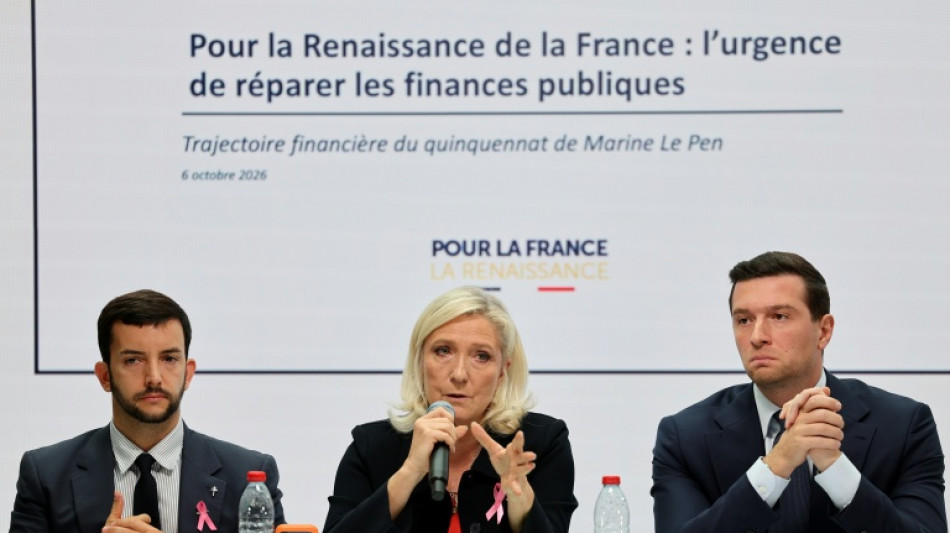
Le Pen recently sought to bolster her economic credentials -- one of the worries during her last presidential run -- by promising 140 billion euros in savings by 2032 and to bring the budget deficit down to three percent by 2030.
fcz-kas-jug/ak/js/rl
(H.Duplantier--LPdF)